Understanding Self-Employed Mortgages
Navigating the mortgage landscape as a self-employed individual in Las Vegas presents unique challenges. Traditional mortgage criteria often diverge from the financial circumstances of self-employed borrowers. This guide clarifies the self-employed mortgage lending landscape in Nevada, outlining options and requirements that cater to your specific needs.
Common Mortgage Options for Self-Employed Individuals
Self-employed borrowers have several tailored mortgage choices. Here are some popular options:
- Tax-Return Mortgages: These utilize IRS tax returns to validate income.
- Bank Statement Loans: Instead of tax returns, lenders assess personal or business bank statements over a period of 12 to 24 months.
- Asset Depletion Loans: This option permits borrowers to qualify based on liquid assets rather than income.
These alternatives ensure that diverse income sources can find a suitable solution for their financial situation.
Documentation Paths for Self-Employed Borrowers
Knowing which documents are necessary can expedite the mortgage process. Here’s what you'll typically need:
Tax Returns
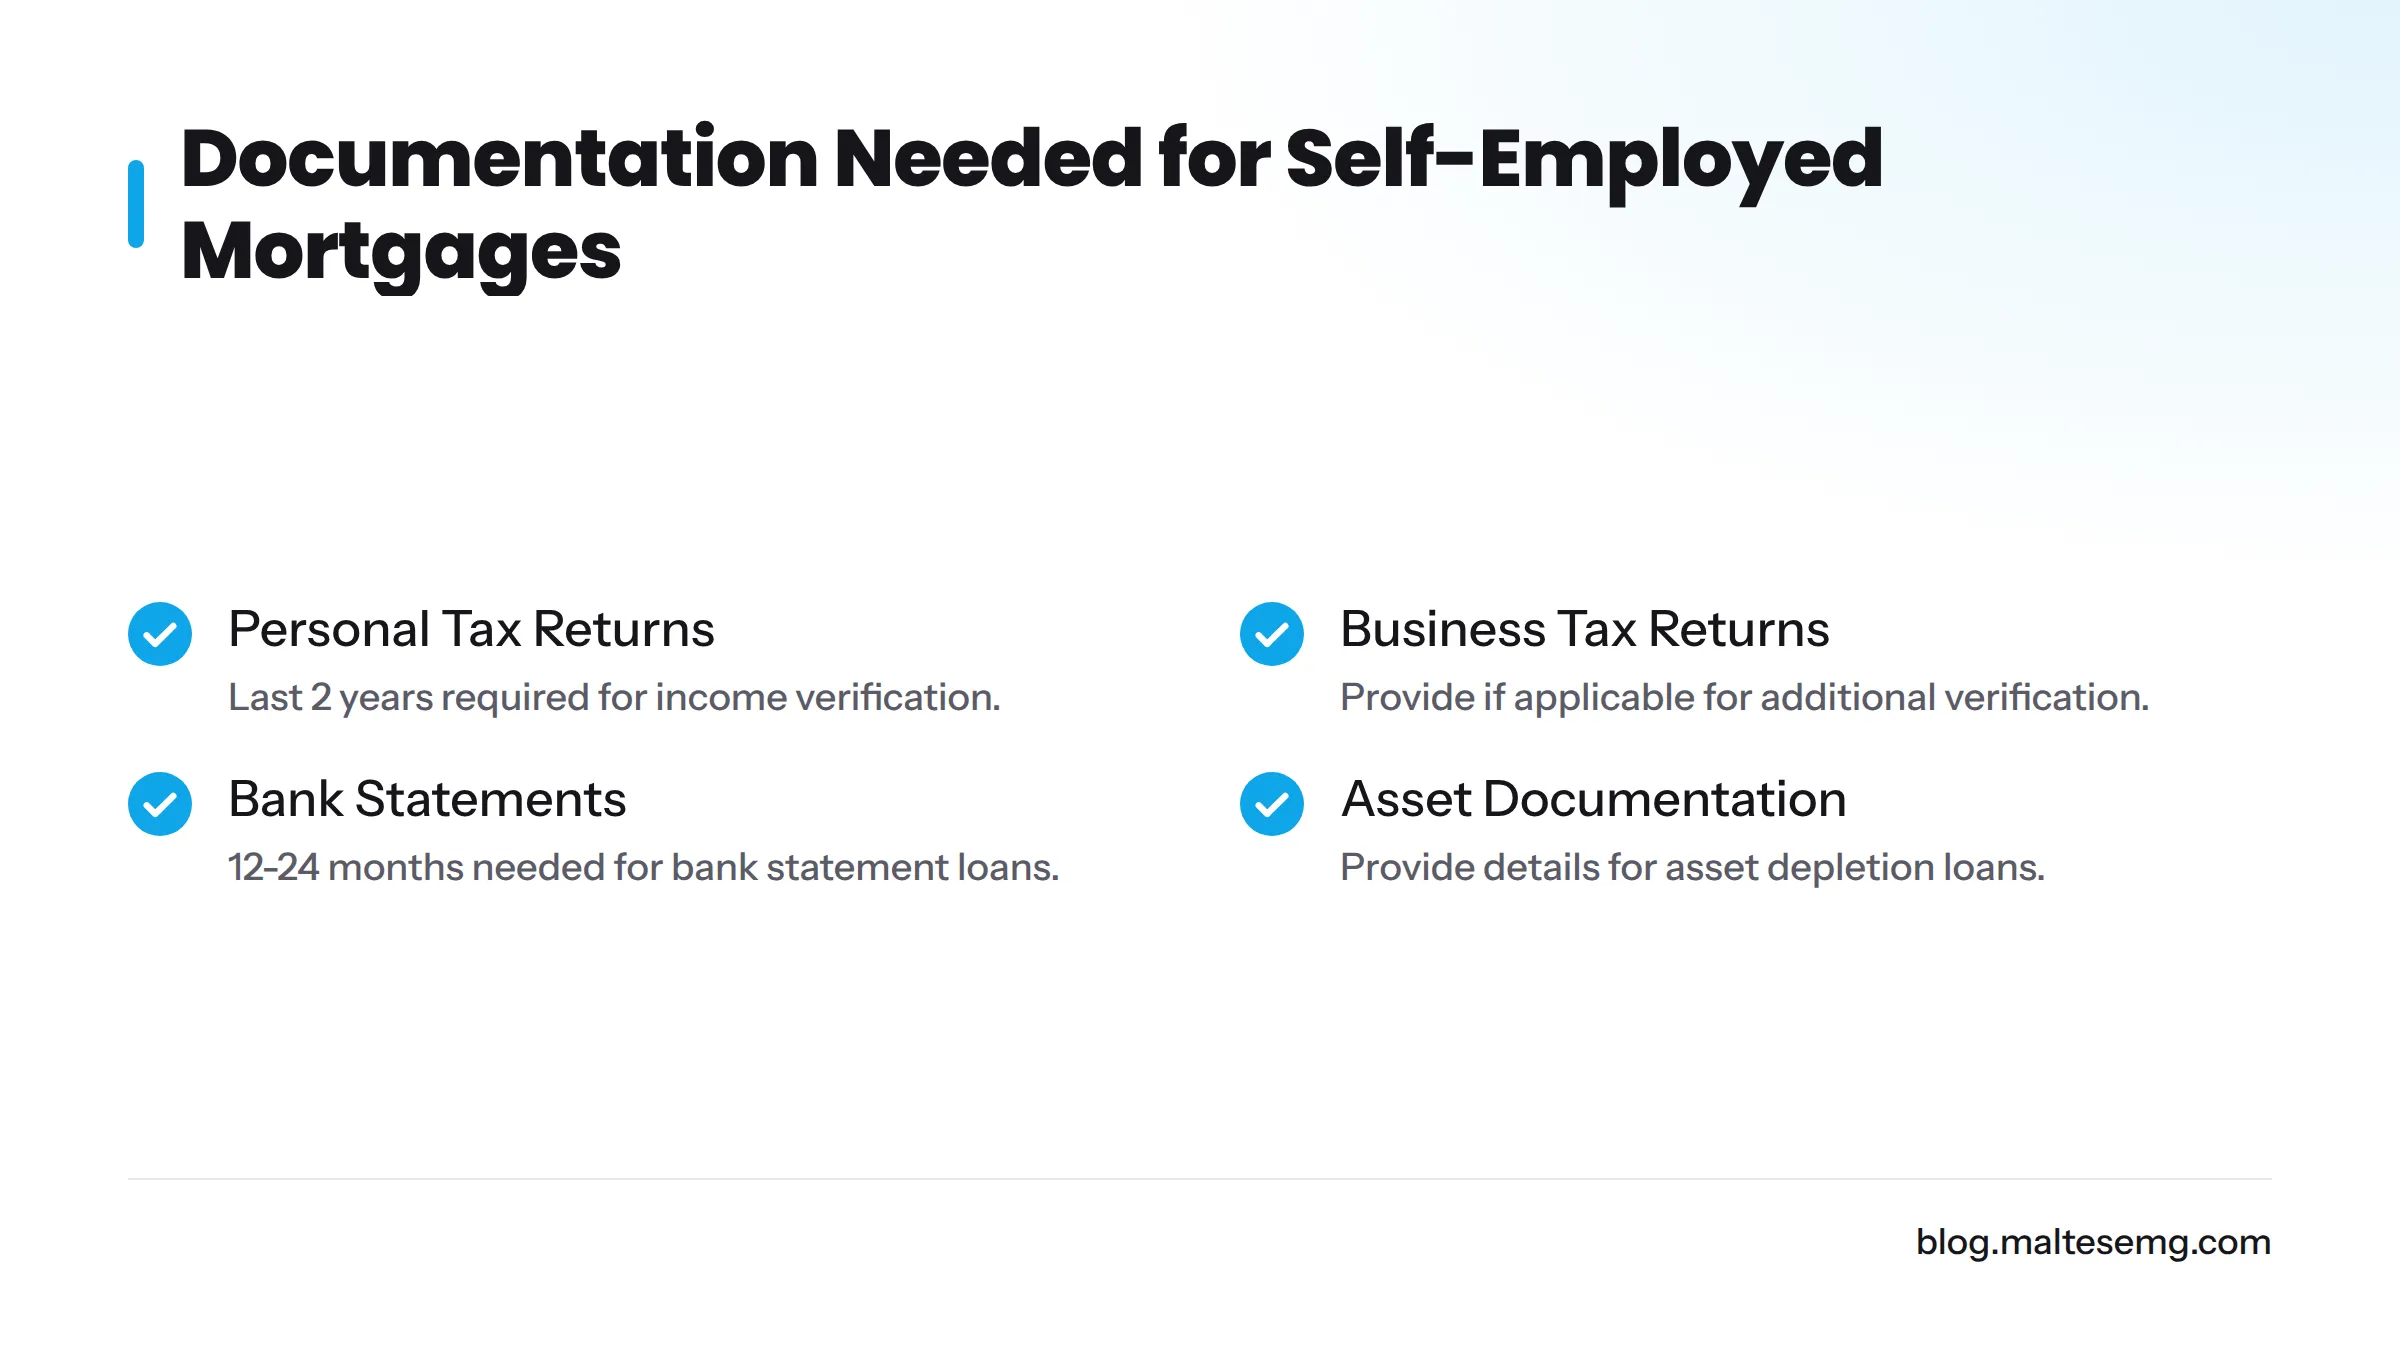
Lenders often require the last two years of personal and any applicable business tax returns to verify income stability.
Bank Statements
For bank statement loans, provide 12–24 months of bank statements that show consistent deposits, accommodating income fluctuations.
Asset-Based Verification
In cases of irregular income, asset depletion allows lenders to assess your ability to repay based on your liquid assets.
Who Qualifies for Self-Employed Mortgages
Lenders generally seek specific criteria for self-employed borrowers:
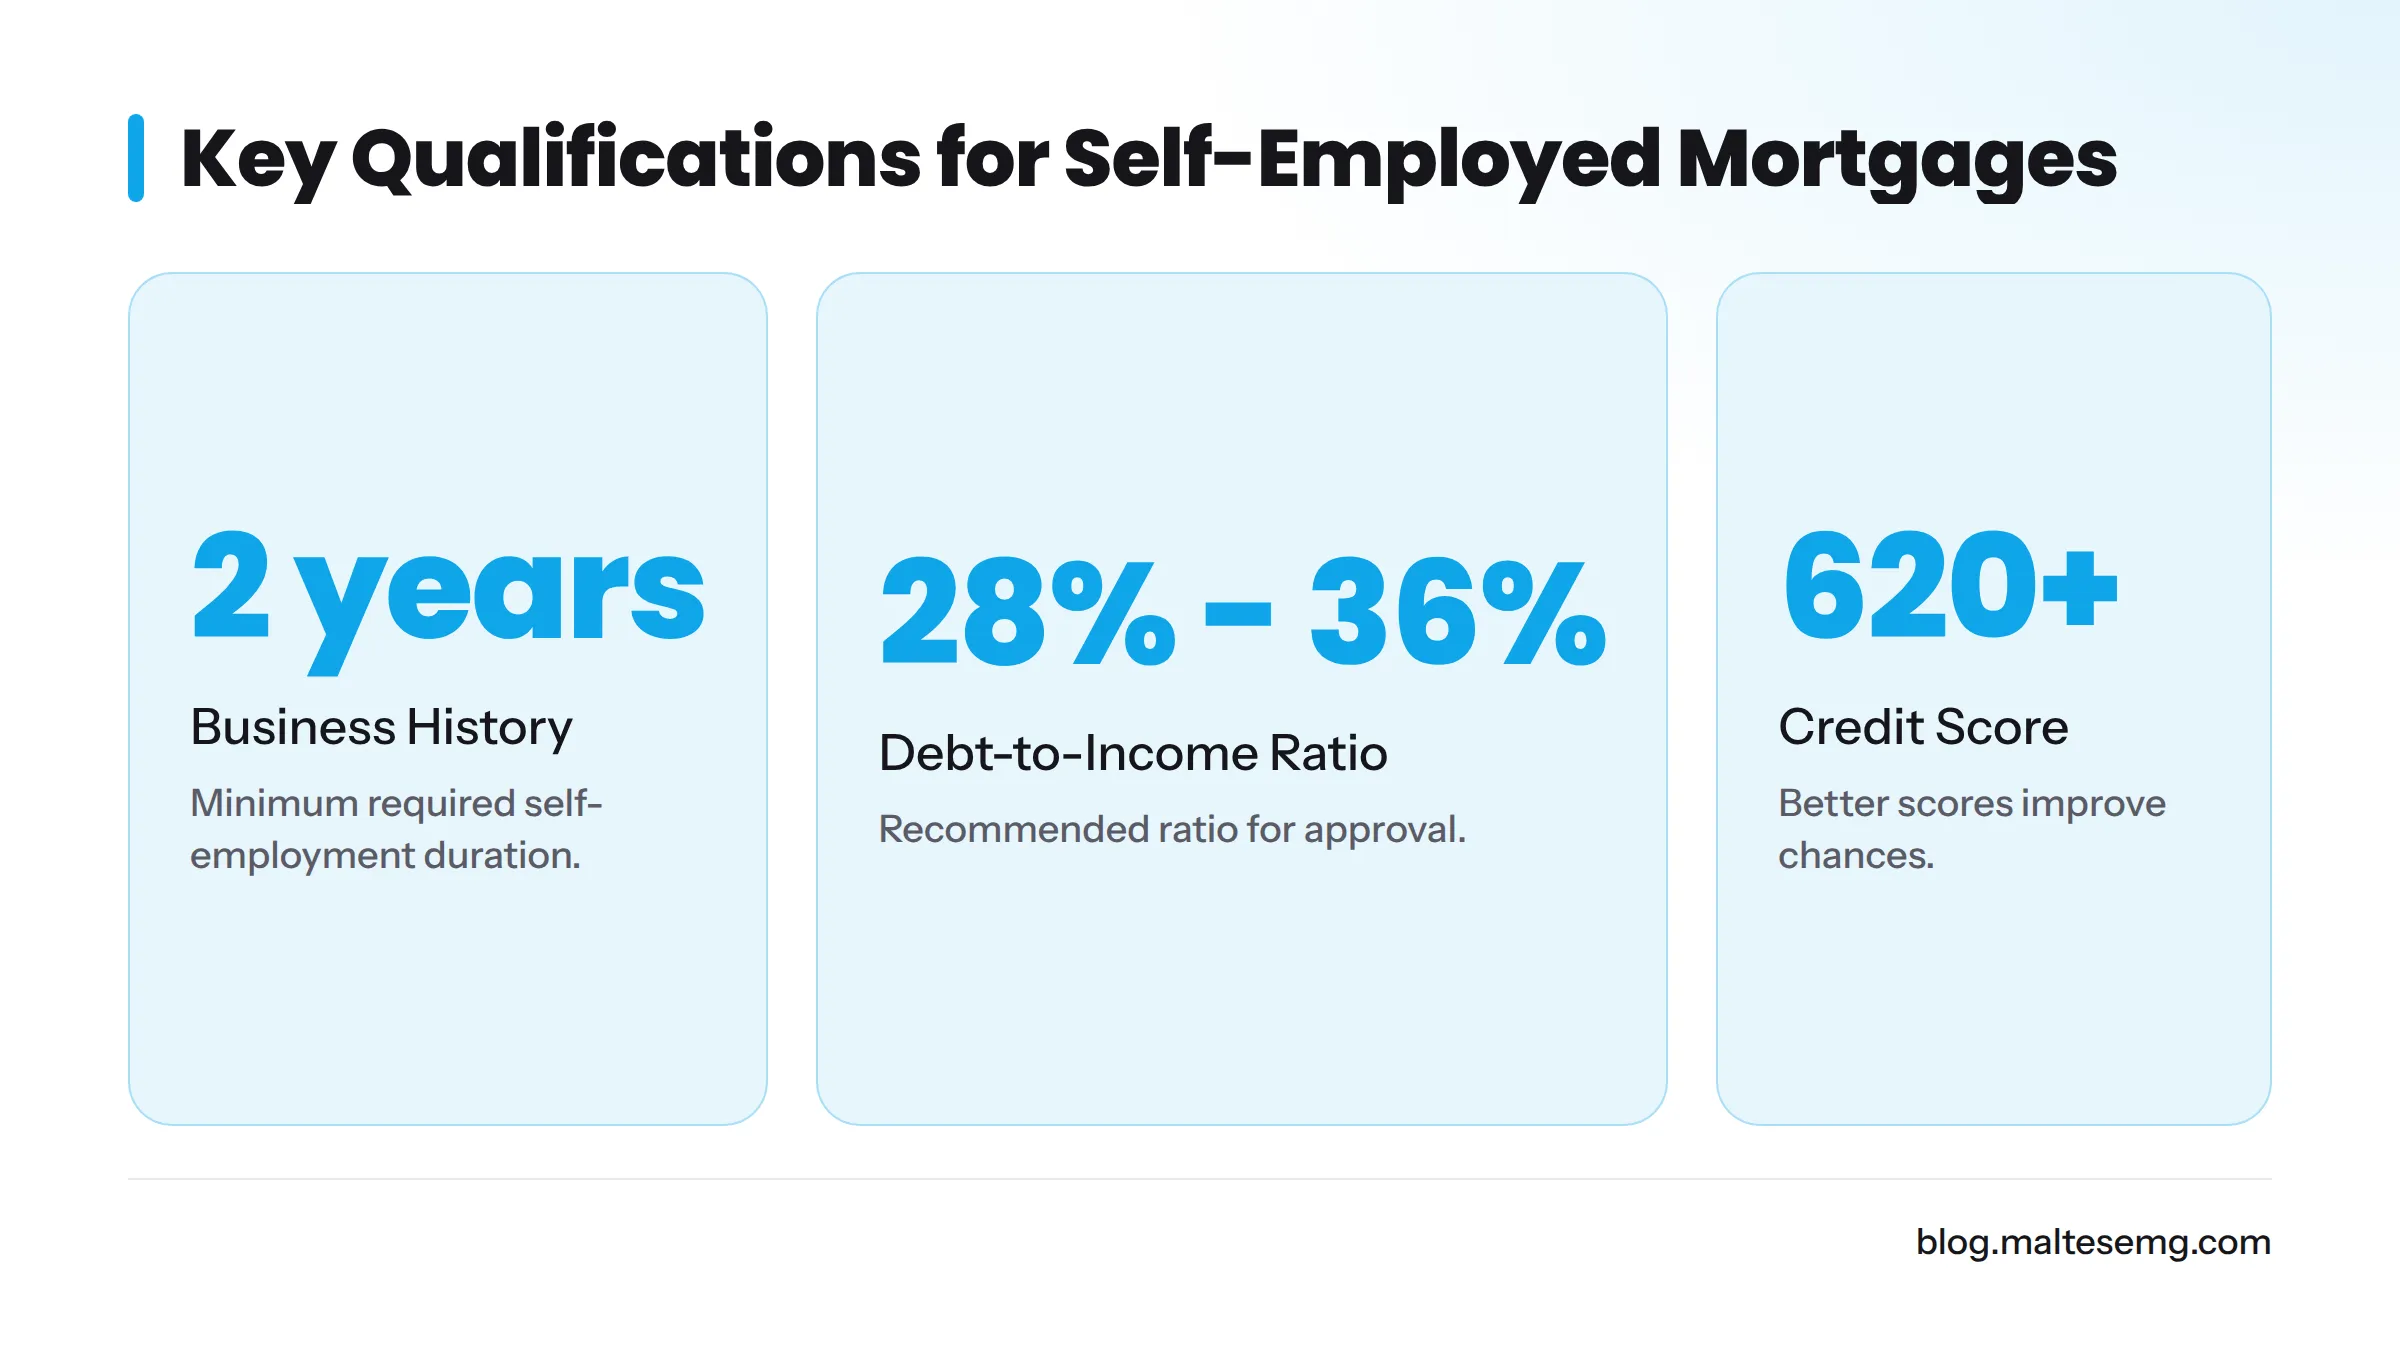
- Business History: Preferably at least two years of self-employment.
- Debt-to-Income Ratio: Aiming for a DTI between 28% and 36% is advantageous.
- Credit Score: A credit score of 620 or above improves approval odds and interest rates.
The Mortgage Process for Self-Employed Borrowers
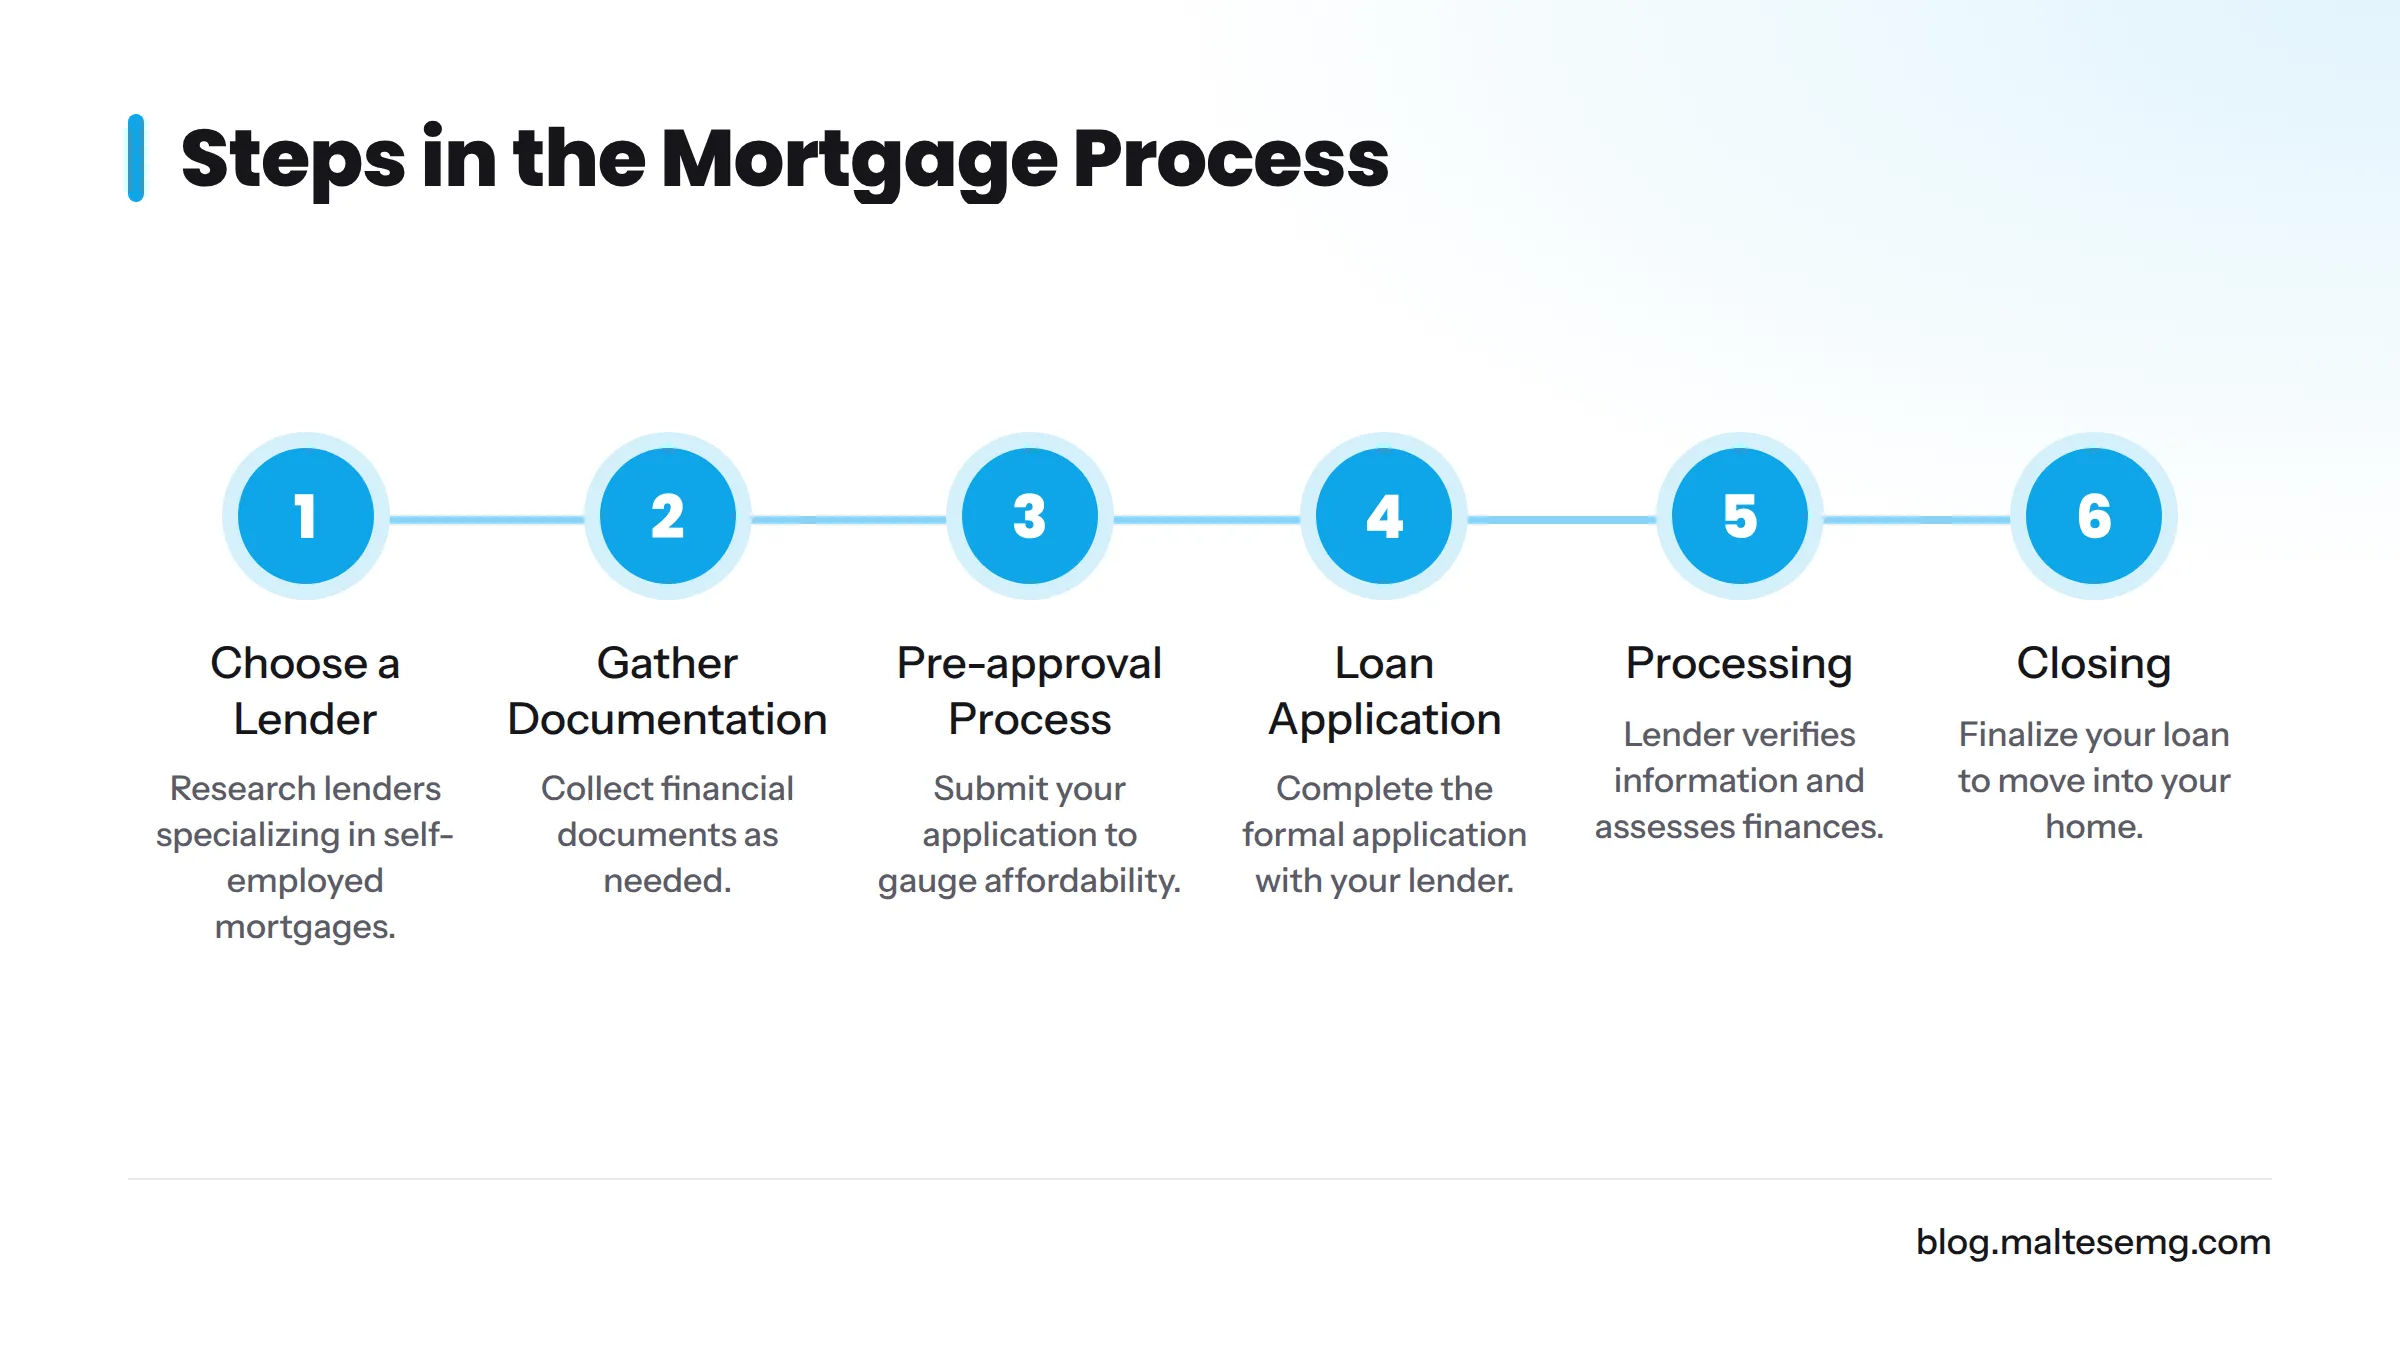
The mortgage process can differ for self-employed individuals. Here’s a simplified outline:
- Choose a Lender: Research lenders specializing in self-employed mortgages.
- Gather Documentation: Collect financial documents as previously outlined.
- Pre-approval Process: Submit your application for pre-approval to gauge your affordability.
- Loan Application: Complete a formal application with your chosen lender.
- Processing: The lender verifies your information and assesses your financial situation.
- Closing: Upon approval, finalize your loan and move into your new home!
Frequently Asked Questions about Self-Employed Mortgages
1. Can I get a mortgage if I'm self-employed?
Yes, numerous lenders offer mortgage products specifically for self-employed individuals.
2. How long do I need to be self-employed to qualify?
Typically, lenders require at least two years of self-employment for loan approval.
3. What if my tax returns show low income due to write-offs?
Consider bank statement or asset-based loans that do not rely solely on tax returns.
4. Do self-employed borrowers pay higher rates?
While rates may be slightly higher due to perceived risk, this varies by lender.
5. What documentation is needed for a bank statement loan?
You'll need several months of bank statements showing regular deposits.
6. What are the most popular mortgage options for self-employed individuals?
Tax returns, bank statements, and asset depletion loans dominate the choices.
7. How can I improve my chances of qualifying for a mortgage?
Maintaining a strong credit score and preparing thorough documentation can help.
8. What are the risks of securing a bank statement loan?
If bank statements do not reflect sufficient income, it may lead to denial.
9. Are there additional fees for self-employed mortgage applications?
Some lenders may charge higher application or processing fees, but this varies.
10. Where can I find local mortgage lenders for self-employed borrowers?
Search for local networks and reviews to find specialized lenders in Las Vegas.
Final Thoughts
As a self-employed individual looking for mortgage options in Las Vegas, understanding your available choices and necessary documentation is crucial. Selecting the right lender can significantly impact your journey to homeownership.
To connect with local lenders who understand your specific needs, explore resources like Mortgage & Market Updates.
Matt Maltese
Branch Manager NMLS 369921
Cardinal Financial Company, Limited Partnership
NMLS: 66247
10845 Griffith Peak Dr 200 03 121
Las Vegas, NV 89135
Sources
- Fannie Mae Self-Employed Guidelines
- Nevada Mortgage Regulations ## Relevant Videos Here are additional resources to help you understand self-employed mortgages better:
Self-Employed Mortgage Guide 2026 | How to Qualify for a Home Loan in Las Vegas
How to Get a Home Loan When You're Self-Employed | ft. Kelsey from G Lending
These guides provide valuable insights specific to the Las Vegas market and self-employed borrowers!