What Are FHA Mortgage Rates?
FHA mortgage rates refer to the specific interest rates for loans insured by the Federal Housing Administration (FHA). These loans aim to make homeownership more attainable for diverse borrowers, including those with lower credit scores or smaller down payments.
Key Definitions
To grasp FHA mortgage rates, let’s clarify some essential terms:
- FHA Loan: A mortgage backed by the FHA that facilitates lower down payments and more flexible credit requirements.
- Mortgage Insurance Premium (MIP): A fee charged by the FHA to ensure the loan, protecting lenders in case of borrower default.
- Annual Percentage Rate (APR): This is the total yearly cost of a loan expressed as a percentage, which includes interest rates and additional costs.
How FHA Mortgage Rates Compare to Conventional Rates
When comparing FHA mortgage rates to conventional loan rates, it's critical to recognize the differences in requirements and costs. Generally, FHA rates are slightly lower than conventional rates, providing a distinct advantage for buyers with lower credit scores. Here’s why:
- Lower Credit Score Requirements: FHA loans may be accessible to borrowers with credit scores as low as 580, while conventional loans typically demand higher scores.
- Down Payment: FHA loans usually require a down payment of just 3.5%, while conventional loans may ask for up to 20%.
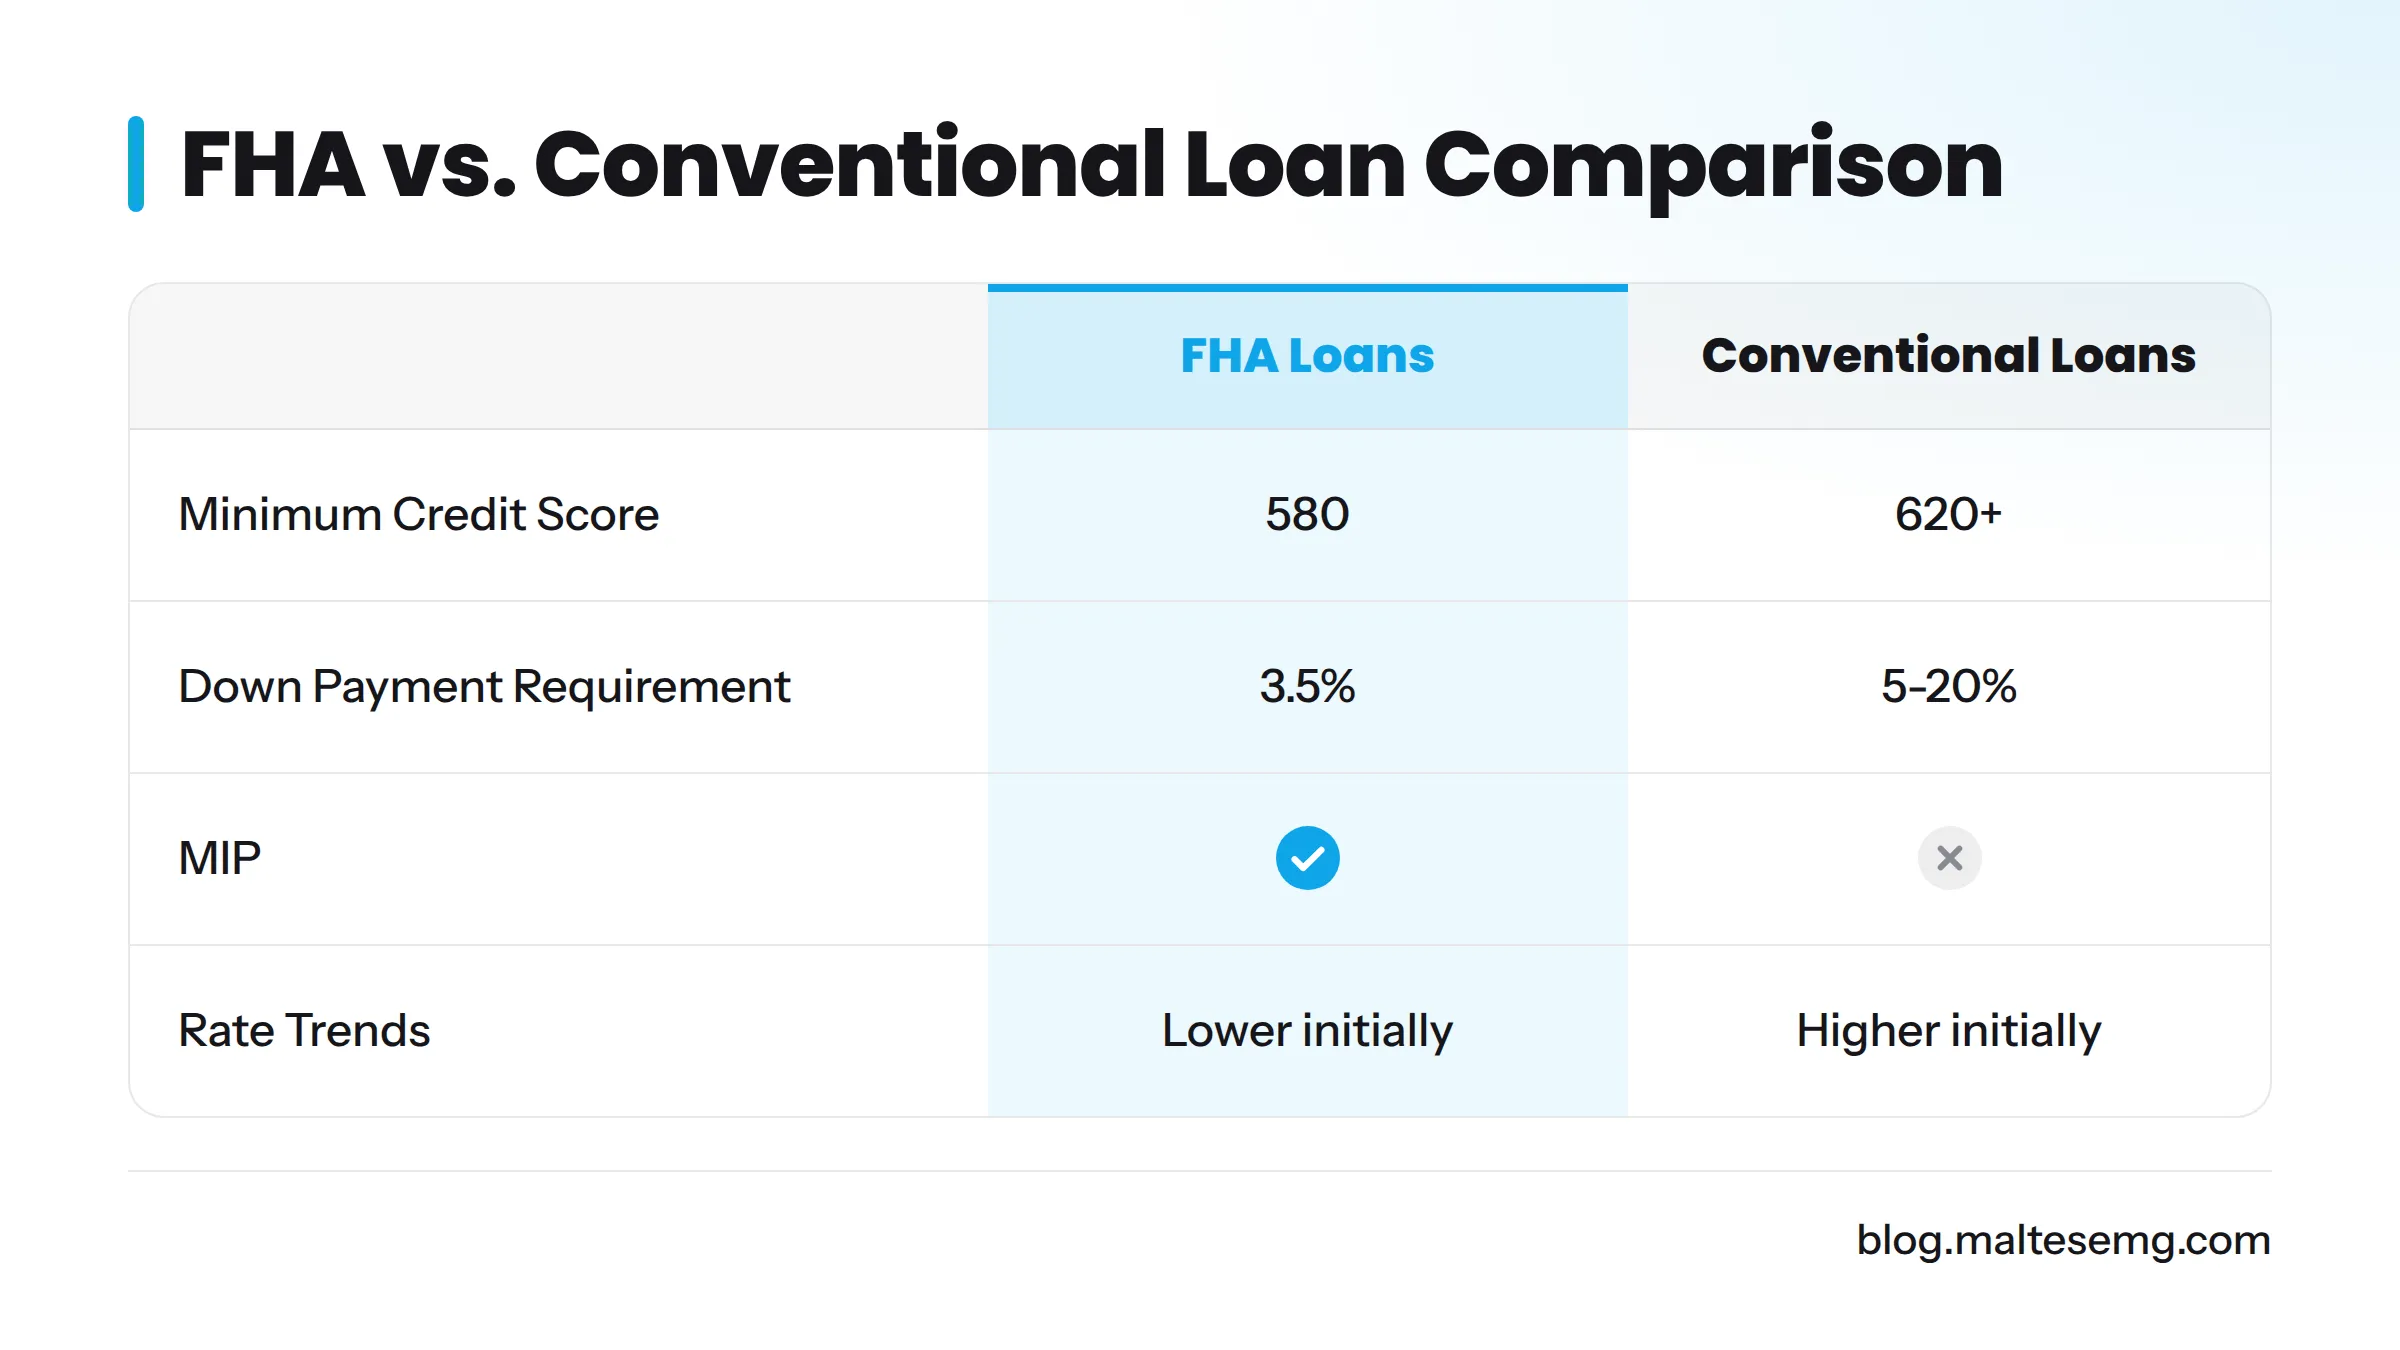
FHA vs. Conventional Rate Comparison
| Feature | FHA Loans | Conventional Loans |
|---|---|---|
| Minimum Credit Score | 580 | 620+ |
| Down Payment Requirement | 3.5% | 5-20% |
| MIP | Yes | No |
| Rate Trends | Lower initially | Higher initially |
This comparison illustrates that FHA loans can offer substantial benefits, particularly for qualifying borrowers.
Understanding Mortgage Insurance Premium (MIP)
MIP plays a significant role in FHA loans, contributing to the overall cost. Borrowers must pay MIP both upfront and annually. Here’s a breakdown:
- Upfront MIP: Usually 1.75% of the loan amount, payable at closing.
- Annual MIP: This varies based on the loan size, down payment, and loan duration, and is incorporated into monthly payments.
Understanding MIP is vital, as it can increase the overall loan cost significantly.
Factors Affecting FHA Mortgage Rates
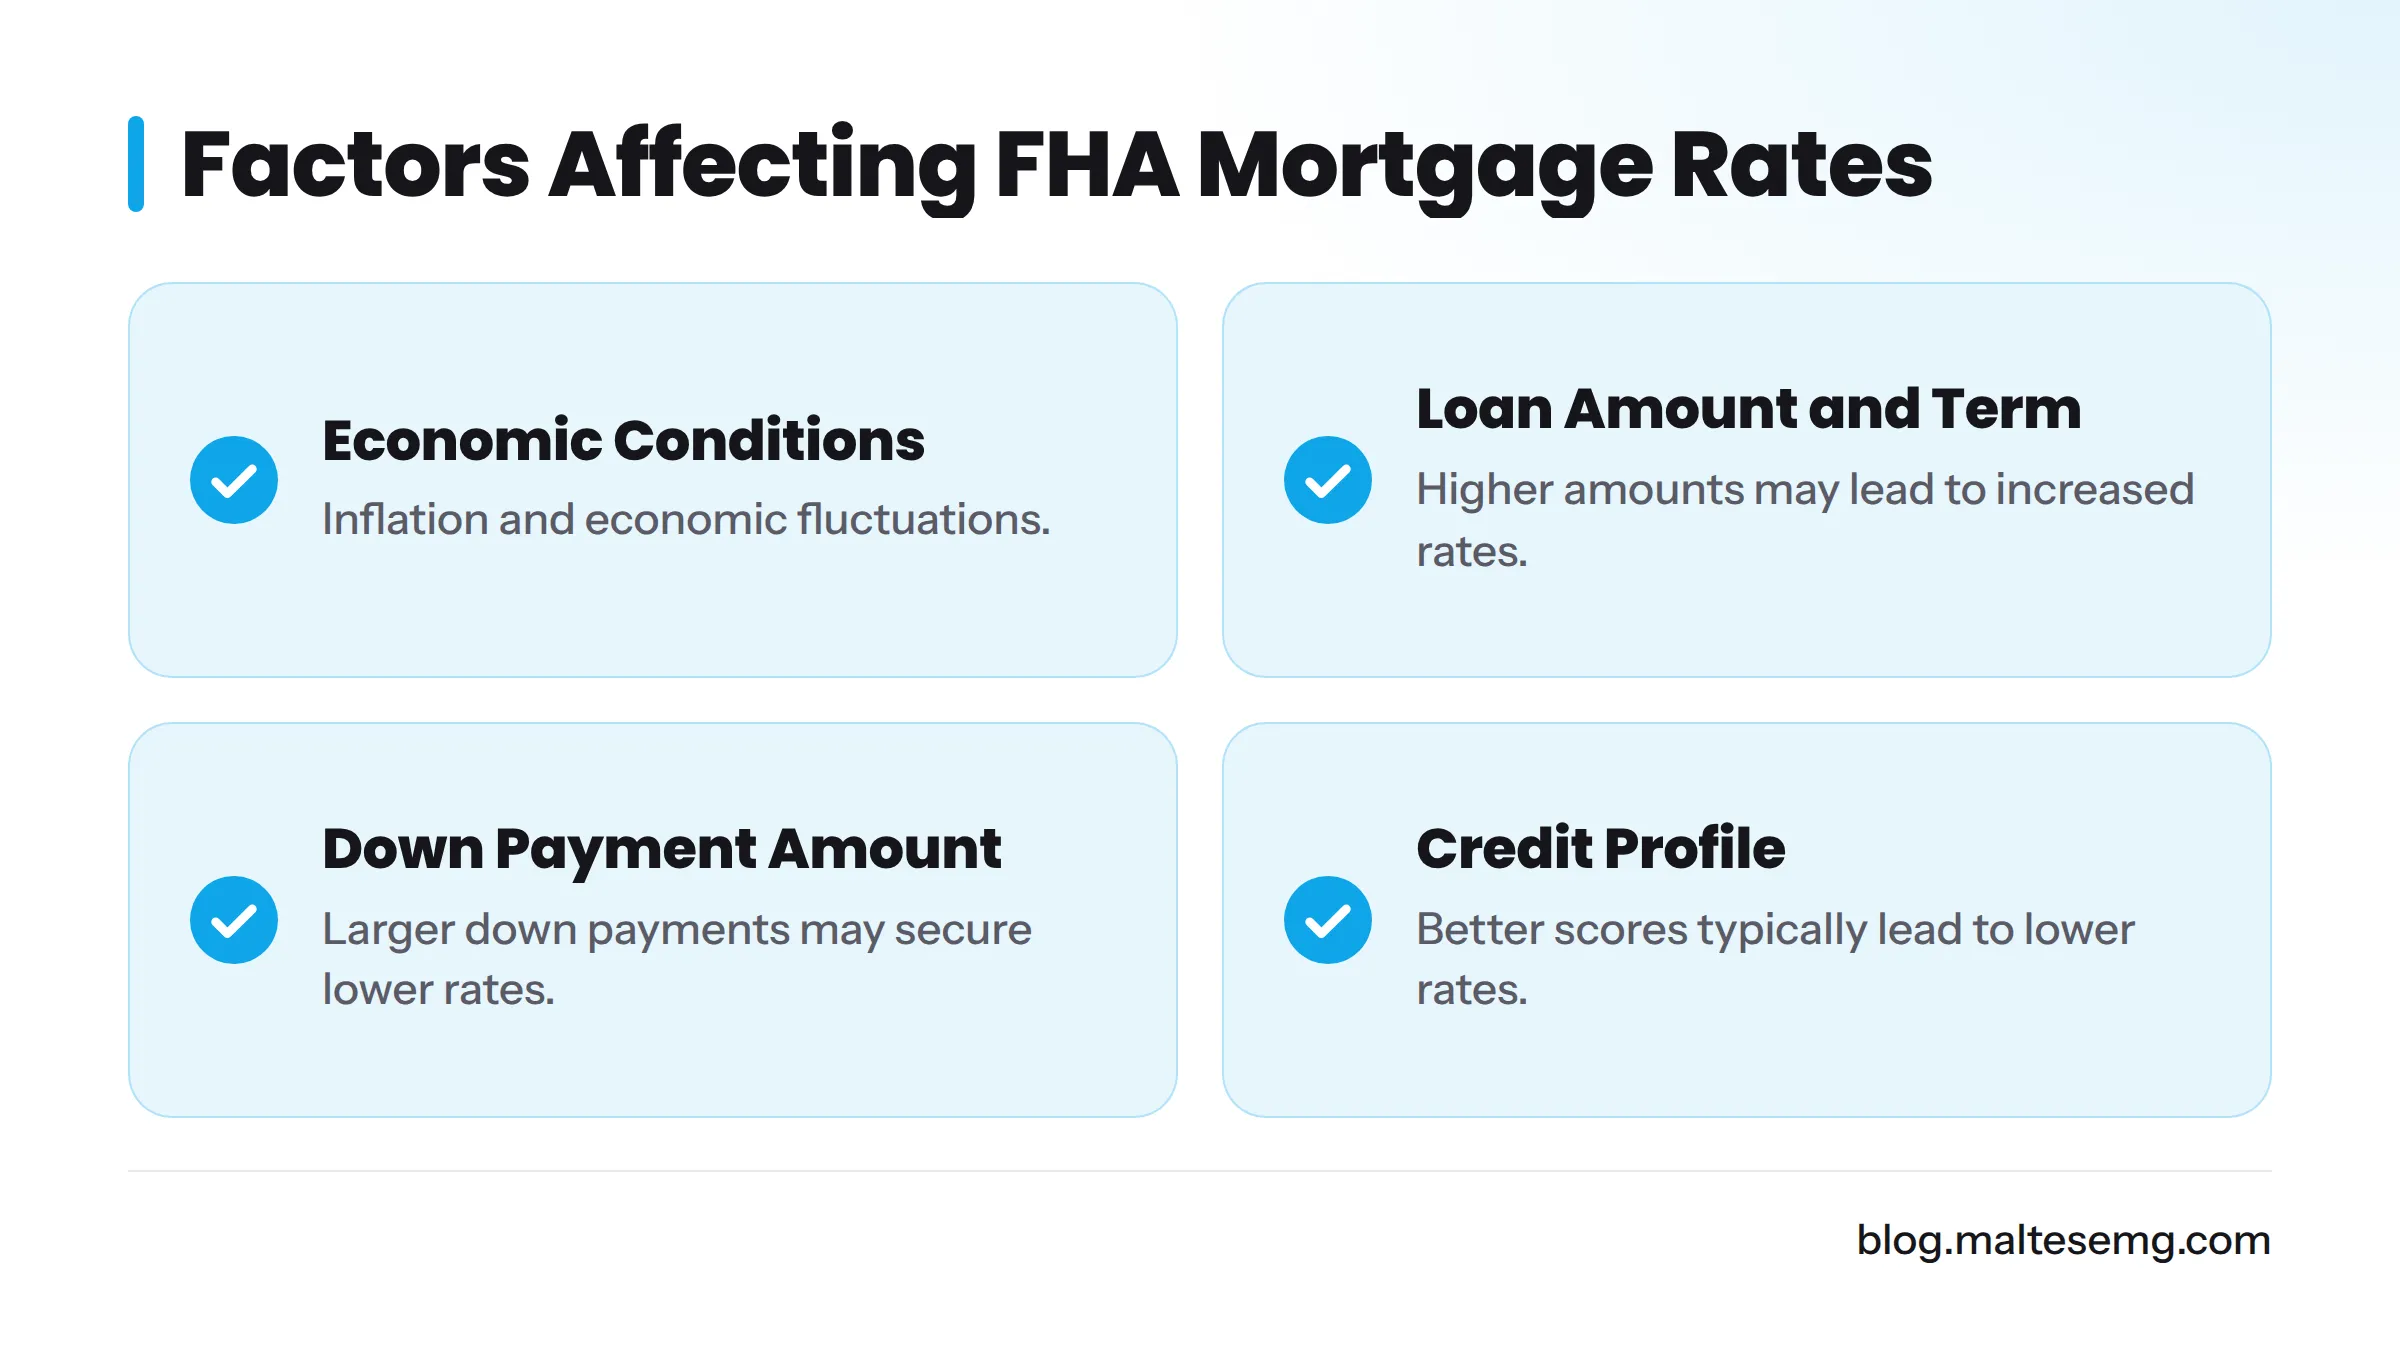
Multiple factors influence FHA mortgage rates:
- Economic Conditions: Economic fluctuations can impact general interest rates.
- Loan Amount and Term: Higher loan amounts and extended terms can lead to increased rates.
- Down Payment Amount: A larger down payment may secure a lower interest rate.
- Credit Profile: Credit scores directly affect the rate; better scores typically lead to lower rates.
Local Perspectives on FHA Loan Costs
Examining FHA loan costs in specific areas provides deeper insights. In Clark County, for example, local factors that could affect rates include:
- Housing Market Trends: Evaluating recent sales and median home prices in the county.
- Local Economic Conditions: Employment rates and the overall economic climate can shape mortgage availability and costs.
Clark County Borrower Scenarios
Analyzing real-life borrower conditions highlights the practical effects of FHA versus conventional rates. For instance, purchasing a $300,000 home with a 3.5% down payment results in significantly lower initial costs compared to a conventional loan requiring a larger down payment.
Conclusion: Evaluating FHA Mortgage Rates for Your Needs
FHA mortgage rates in 2026 present numerous advantages for eligible buyers, especially in comparison to conventional loans. Understanding MIP's interaction and how local factors influence these rates will help you make informed choices about your mortgage.
For tailored advice and insights on your specific mortgage situation, please reach out.
Contact Information:
Matt Maltese Branch Manager NMLS 369921
Cardinal Financial Company, Limited Partnership NMLS: 66247
10845 Griffith Peak Dr 200 03 121
Las Vegas, NV 89135
FAQ
- What are FHA mortgage rates? FHA mortgage rates are the interest rates for loans insured by the FHA, focusing on accessible homeownership opportunities.
- How do FHA rates compare to conventional rates? FHA rates are often lower for borrowers with low credit scores or small down payments, making them an attractive option.
- What factors influence FHA mortgage rates? Key factors include economic conditions, loan amount, down payment, and the borrower’s credit profile.
- Are FHA rates lower than conventional rates? Yes, particularly for borrowers with lower credit scores and smaller down payments.
- Can I get an FHA loan with a low credit score? Yes, FHA loans may be available for those with credit scores as low as 580.
- How does mortgage insurance impact my FHA loan cost? MIP increases your overall loan cost, affecting monthly payments and total amounts.
- What is the down payment requirement for FHA? FHA requires a minimum down payment of 3.5% of the home's price.
- Are FHA loans only for first-time buyers? No, FHA loans can be accessed by anyone meeting eligibility criteria.
- Can I refinance my FHA loan? Yes, refinancing options are available for FHA loans.
- How often do FHA mortgage rates change? FHA mortgage rates can frequently fluctuate based on market conditions.
For further reading, explore our articles on Las Vegas mortgage rates, the current FHA MIP chart, and FHA vs conventional loans.
Sources
Related: Las Vegas mortgage rates