Overview of Home Loans in Las Vegas, NV
Las Vegas offers a vibrant market for home loans, catering to both experienced homeowners and those looking to upgrade. With an array of options including conventional and FHA loans, understanding your choices is vital for making smart financial decisions. Local professionals, like Matt Maltese, can guide you through the details of home financing in this dynamic market.
Understanding Conventional Home Loans
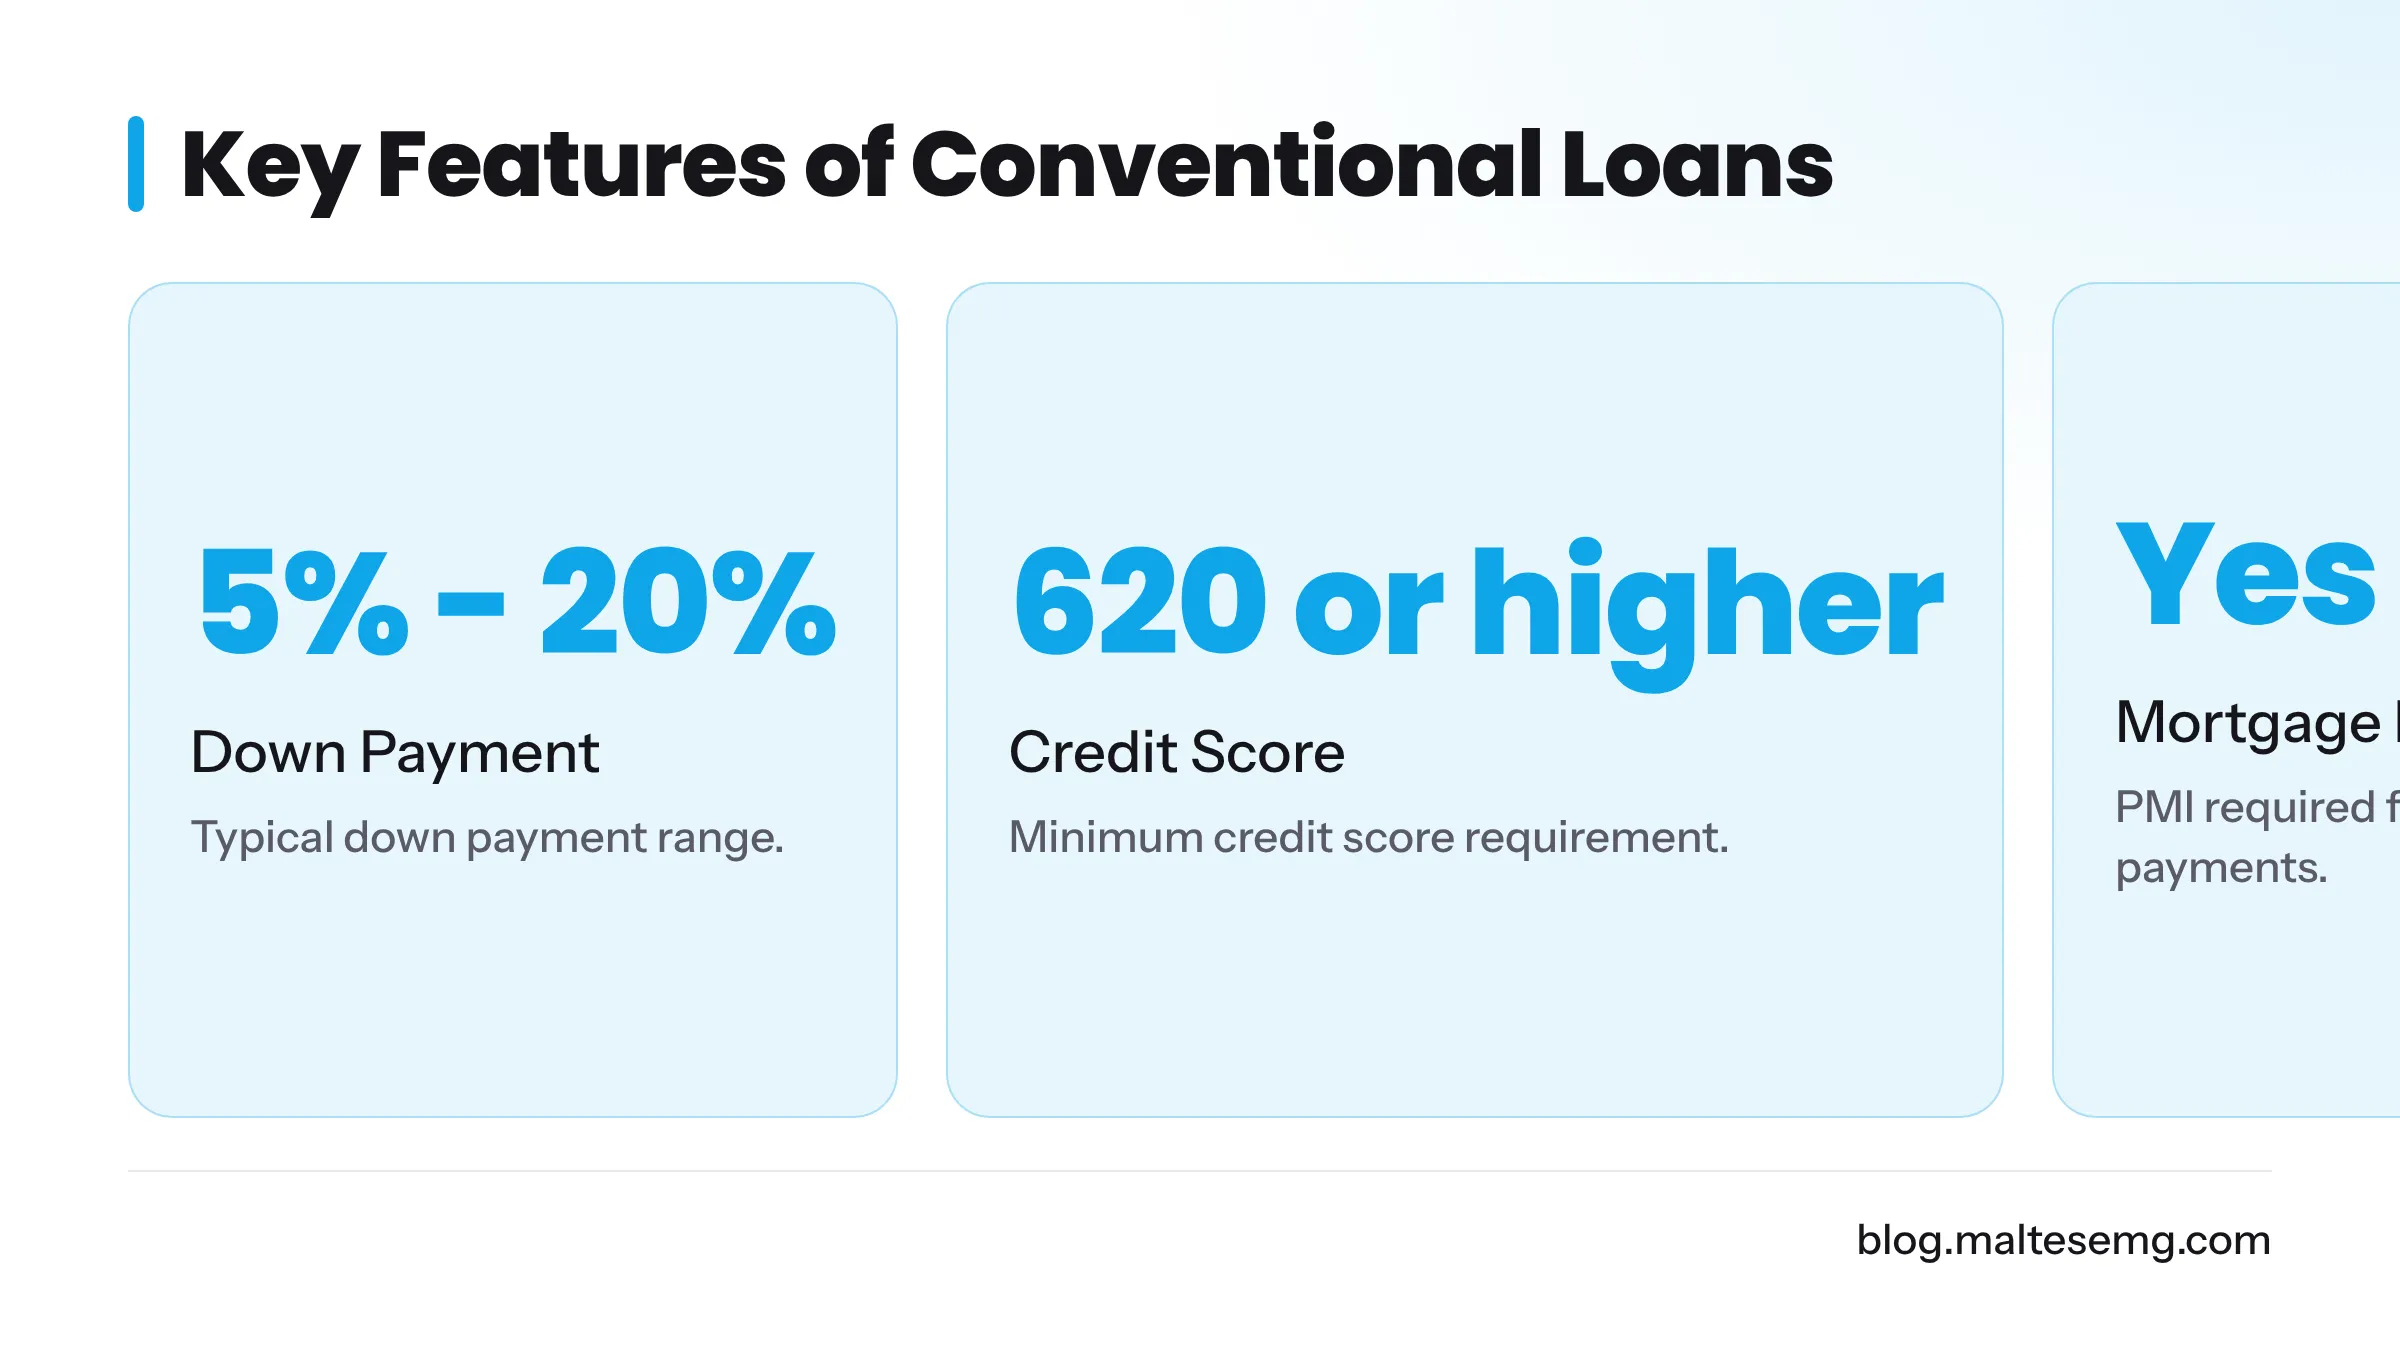
Conventional home loans are not backed by government agencies. This type of financing typically demands higher credit scores and larger down payments than FHA loans. Key features include:
- Down Payment: Generally between 5% and 20%.
- Credit Score Requirements: Usually higher, starting at 620 or more.
- Mortgage Insurance: Private mortgage insurance (PMI) is mandated if your down payment is less than 20%.
Conventional loans are ideal for borrowers with strong credit histories aiming to buy a home without government stipulations.
Exploring FHA Home Loans
FHA loans, secured by the Federal Housing Administration, provide more accessible options for buyers with lower credit scores and lesser down payments. Main characteristics are:
- Down Payment: As low as 3.5% for qualified applicants.
- Credit Score Requirements: Acceptable scores can start at 580.
- Mortgage Insurance Premium (MIP): Necessary for the duration of the loan.
FHA loans are suitable for those who might find conventional financing challenging due to credit issues.
Comparison of Conventional and FHA Loans
| Feature | Conventional Loans | FHA Loans |
|---|---|---|
| Down Payment | 5% - 20% | As low as 3.5% |
| Credit Score | 620 or higher | 580 or higher |
| Mortgage Insurance | PMI if down payment < 20% | MIP applies to most borrowers |
| Loan Limits | Determined by Fannie Mae/Freddie Mac | Based on Clark County regulations |
| Ideal For | Borrowers with solid credit | Home buyers with lower credit |
Both loan types have unique advantages and disadvantages; your selection should align with your financial circumstances and future aspirations.
Steps to Apply for a Home Loan in Las Vegas
- Verify Your Eligibility: Gather essential financial documents, including credit reports and income statements.
- Select a Loan Type: Choose between conventional and FHA loans based on your needs.
- Locate a Local Lender: Consult with a local lending institution for expert guidance. For great local expertise, reach out to Matt Maltese at Cardinal Financial.
- Submit Your Application: Fill out your application with the required documents, plus any additional information your lender might need.
- Await Approval: Your lender will assess your application. If approved, you’ll receive a detailed loan estimate.
For detailed insight on the application process, reference Types of mortgage loans explained or Comparing FHA and conventional loans.
Important Factors When Choosing a Loan
- Credit Score: Understand your credit score, as it dramatically influences your eligibility and loan terms.
- Down Payment Amount: Assess what you can comfortably pay upfront.
- Long-term Aspirations: Consider your homeownership goals and potential refinancing needs in the future.
- Market Climate: Stay informed on current interest rates and the real estate landscape in Las Vegas.
Local Resources for Home Buyers
Las Vegas offers an array of resources for home buyers seeking local support. Examples include:
- Matt Maltese, Branch Manager: With extensive experience, he provides personalized assistance tailored to local market needs at Cardinal Financial, located at 10845 Griffith Peak Dr Ste 200, Las Vegas, NV 89135.
- Community Workshops: These sessions often deliver valuable insights into the home-buying journey and financing options.
Secure a Quote for Your Home Loan
Contacting a local lender for a tailored quote is a proactive step. With Matt Maltese's expertise, you can discuss the best loan options and secure financing that meets your needs. Schedule a consultation today!
FAQs
What differentiates a conventional loan from an FHA loan?
A conventional loan is not government-backed and generally calls for higher credit scores, whereas an FHA loan, insured by the Federal Housing Administration, is more accessible for those with lower credit scores and enables a smaller down payment.
How much of a down payment is required for a home loan in Las Vegas?
Down payments can vary from 3.5% for FHA loans to 5% or more for conventional loans, depending on lender guidelines and your creditworthiness.
Do you provide loans in Henderson, Summerlin, and North Las Vegas?
Yes, we offer local lending options in these areas to support your home financing needs.
Which loan option is better if my credit is less than ideal?
FHA loans are often preferable for those with lower credit scores, as they are designed for wider accessibility.
For personalized assistance or specific information about available lending options in Las Vegas, visit The Maltese Group - Cardinal Financial.
Matt Maltese
Branch Manager NMLS: 369921
Cardinal Financial Company, Limited Partnership
NMLS: 66247
10845 Griffith Peak Dr Ste 200
Las Vegas, NV 89135
Related: VA home loans for military borrowers, jumbo financing for higher-priced homes, today's Las Vegas mortgage rates