Understanding Mortgage Refinancing
Refinancing a mortgage means replacing your current loan with a new one that ideally offers better terms. Homeowners generally pursue this option to lower monthly payments, reduce interest rates, or tap into home equity. In 2026, the choice to refinance hinges on current interest rates, individual financial situations, and various costs associated with the process.
Key Factors to Consider
When weighing the benefits of refinancing, pay attention to these crucial factors:
- Current Interest Rates: Compare your existing mortgage rate to the current market rates. A significantly lower rate may justify refinancing.
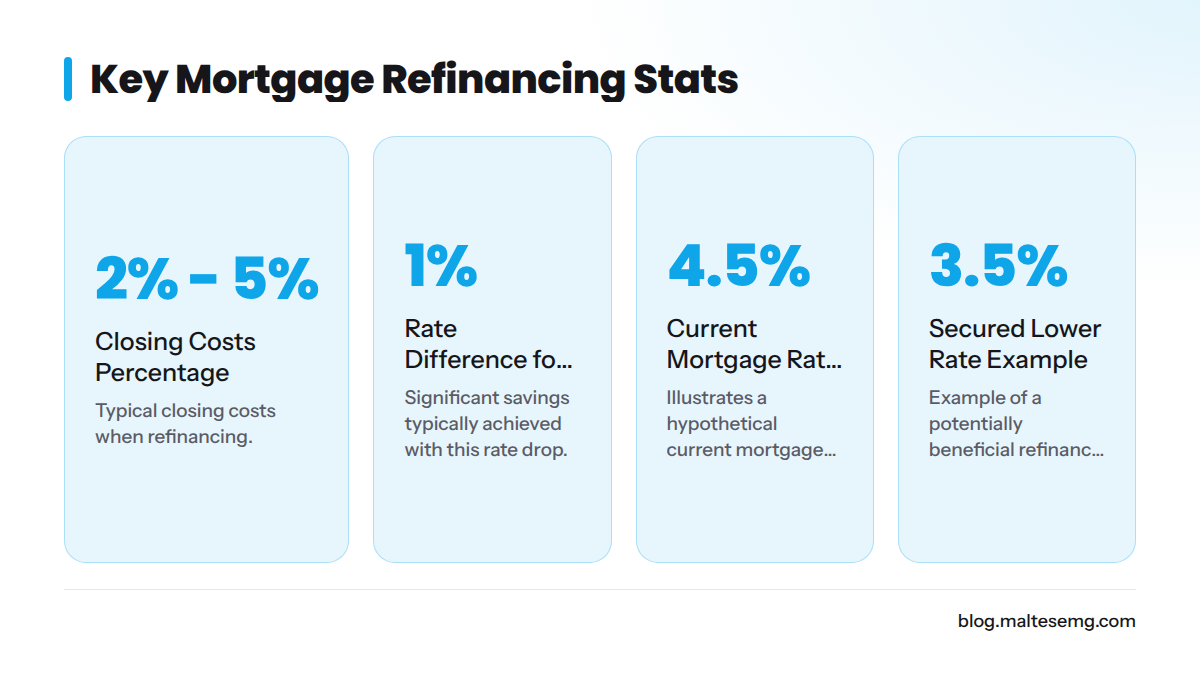
- Closing Costs: These include appraisal fees, title insurance, and loan origination fees, which can total between 2% and 5% of the loan amount.
- Credit Score: Your credit score impacts the terms lenders may offer. A higher score often yields more favorable rates.
- Loan Terms: Evaluate the new loan term against your current one. A shorter term may increase monthly payments but significantly lower the total interest paid over the life of the loan.
When Is Rate Difference Significant?
A common guideline suggests that refinancing may be worthwhile if you can lower your interest rate by at least 1%. For instance, if your current mortgage rate is 4.5% and you secure a 3.5% rate, you could save a substantial sum over time.
Calculating Closing Costs
Understanding the closing costs is essential for determining if refinancing is a wise financial decision. Common costs may include:
- Application Fees: A charge that lenders may require to process your refinance application.
- Appraisal Fees: Necessary to assess your home's value.
- Credit Report Fees: For checking your credit score.
- Title Insurance: Safeguards against ownership disputes.
| Type of Cost | Estimated Cost |
|---|---|
| Application Fee | $300 - $500 |
| Appraisal Fee | $300 - $700 |
| Credit Report Fee | $30 - $50 |
| Title Insurance | $1,000 - $2,500 (varies by state) |
Time-to-Breakeven Analysis
To determine if refinancing makes economic sense, identify your breakeven point by dividing the total closing costs by the monthly savings from your new mortgage payment. For example, with refinancing costs of $4,000 and monthly savings of $200, the breakeven point would be:
Breakeven Point = 4000 / 200 = 20 months
Thus, you would recoup your closing costs in 20 months.
Real Case Studies from Clark County
Here are real-world examples from Clark County that illustrate the benefits of refinancing:
- Case Study 1: A homeowner with a 4.2% mortgage refinanced to a 3.1% rate, achieving monthly savings of $250. The closing costs amounted to $3,500, resulting in a breakeven point of 14 months.
- Case Study 2: A property owner executed a cash-out refinance to withdraw $20,000 for home renovations at a new rate of 3.7%. This strategy aimed to enhance property value and improve financial standing despite the costs involved.
Is Refinancing Worth It for You?
Ultimately, whether refinancing is worth it depends on your individual circumstances. Evaluating costs, potential savings, and specific financial objectives is essential. Consulting with a mortgage broker or financial expert can help tailor an effective refinancing strategy.
FAQ
What is the 2% rule for refinancing?
The 2% rule indicates that refinancing might be advantageous if you can lower your mortgage interest rate by at least 2% compared to your existing rate.
What are the cons of refinancing?
Potential downsides include higher closing costs, extending the loan term, and the risk of incurring costs if you don't maintain the loan long enough to make it beneficial.
How much does it cost to refinance a $300,000 home?
Refinancing a $300,000 home may cost between $6,000 and $10,000, significantly influenced by the lender and location of closing costs.
Final Thoughts
If refinancing your mortgage is on your mind, carefully consider these factors to make an informed decision in 2026. For personalized advice, don't hesitate to reach out to a professional.
Helpful Resources
- For expert tips, visit our page on Expert Home Refinancing Tips for 2026.
- Learn more about the benefits of working with a mortgage broker here.
Matt Maltese
Branch Manager
NMLS 369921
Cardinal Financial Company, Limited Partnership
NMLS: 66247
10845 Griffith Peak Dr 200 03 121
Las Vegas, NV 89135
YouTube Videos for Further Insights
Explore these informative videos for a better understanding of refinancing:
Refinance 101- Mortgage Refinance Explained in 2026
Is Refinancing Your Home Really Worth It in 2026?
These resources are invaluable for making informed decisions about your mortgage refinancing options this year!